
Why the Highest Offer on Your Home Isn't Always the Best Offer
Krista Hartmann
Comfortable and confident – those are some of the feelings you come away with after meeting Krista...
Comfortable and confident – those are some of the feelings you come away with after meeting Krista...
Your home hits the market, showings begin, and then you get the news every seller hopes to hear:
"We have multiple offers."
Even better, one buyer has offered more money than everyone else.
Easy decision, right?
Not necessarily.
After helping St. Louis area homeowners sell their homes since 2014, I've reviewed a lot of offers. One of the most important things I explain to sellers is that the highest offer and the best offer are not always the same thing.
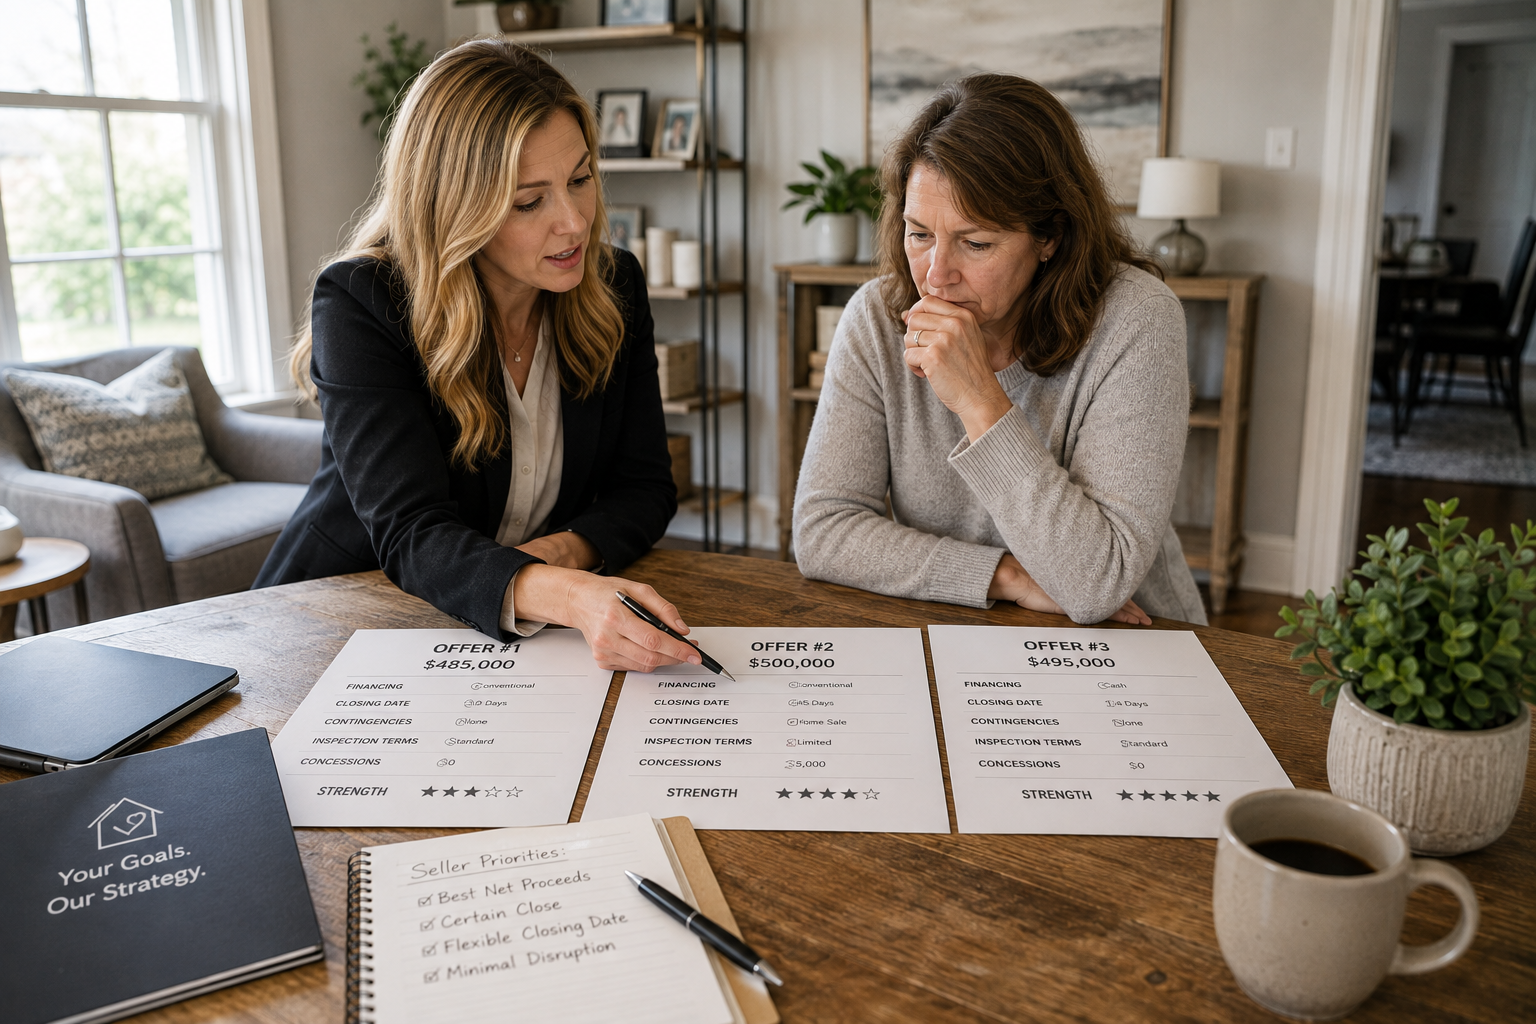
Purchase price certainly matters. But an offer is actually a package of price, financing, contingencies, deadlines, closing terms, and risk.
My job is to help sellers understand that complete package before deciding which buyer they want to move forward with.
Start With Price—But Don't Stop There
Of course we're going to look at the purchase price.
If one buyer is offering $500,000 and another is offering $485,000, that $15,000 difference deserves attention.
But before automatically choosing the $500,000 offer, I want to know what comes with it.
Is that buyer asking you to contribute toward closing costs?
Are they financing nearly the entire purchase?
Is their offer contingent upon selling another home?
What are their inspection terms?
What happens if the appraisal comes in below $500,000?
Now let's look at the $485,000 offer.
Perhaps that buyer has strong financing, isn't asking for seller concessions, has terms that provide greater certainty, and can accommodate exactly when you want to close.
Suddenly, the decision isn't quite as obvious.
That's why I go through each offer with my sellers carefully.
Financing Matters
One of the first things I look at is how the buyer plans to purchase the home.
If they're financing, we want to know whether they're pre-approved and what type of financing they're using.
We may also look at how much they're putting down and whether anything about the financing could potentially affect the transaction.
A very high offer isn't particularly valuable to a seller if the buyer ultimately can't obtain financing and make it to closing.
This is also where communication between agents matters.
If I have questions about an offer, I may speak with the buyer's agent or lender, as appropriate, to better understand the buyer's financial position.
The goal isn't to invade anyone's privacy.
It's to help my seller evaluate the strength of the contract they're considering.
Appraisal Risk Can Change the Equation
Let's say your home is listed for $450,000.
You receive multiple offers, and the highest is $475,000.
That's exciting.
But if the buyer is financing the purchase, we need to consider what happens if the property doesn't appraise for $475,000.
An appraisal gap provision or other agreed-upon terms may affect how much risk the seller faces if the appraisal comes in low.
Without protection, that impressive $475,000 offer may eventually turn into another negotiation.
That doesn't mean we shouldn't accept it.
It simply means I want my sellers to understand the possibilities before they sign.
A number on a contract isn't the same thing as money in your pocket at closing.
Our goal is to evaluate both potential return and likelihood of a successful closing.
A Home Sale Contingency Can Matter
Another important consideration is whether the buyer needs to sell a home before purchasing yours.
A contingent offer isn't automatically a bad offer.
There are situations where it can make perfect sense.
But it introduces another moving part into the transaction.
Now our closing may depend not only on our buyer but also on the successful sale and closing of another property.
If we're comparing two otherwise similar offers and one buyer is non-contingent while the other needs to sell a home first, that's something my seller needs to understand.
The best decision will depend on the circumstances.
Inspection Terms Can Be Important
Inspection terms are another area where offers can differ considerably.
One buyer may submit the highest price but include inspection terms that create more uncertainty for the seller.
Another buyer may submit a slightly lower price with terms that are more attractive.
I don't believe sellers should automatically choose an offer based on inspection language alone, just as I don't think they should choose one based solely on price.
Instead, we evaluate the complete contract.
What protections does the buyer have?
What potential risks does the seller have?
How do those terms compare with the other offers?
Then we make an informed decision.
Seller Concessions Affect Your Bottom Line
Here's another easy detail to overlook.
Imagine Buyer A offers $510,000 but asks the seller for $10,000 toward allowable closing costs.
Buyer B offers $505,000 without requesting that contribution.
Which is financially better?
You can't answer simply by looking at the purchase price.
We need to look at the estimated net proceeds and the rest of the terms.
That's why, when I'm helping sellers compare offers, I don't want them getting distracted by one exciting number at the top of the contract.
We need to understand what each offer may actually mean to them.
Closing Date Can Be More Valuable Than You Think
Sometimes the best term in an offer has nothing to do with money.
I've worked with many clients who are buying and selling at the same time.
If you need the proceeds from your current home for your next move—or you're trying to coordinate two closings—the timing can be extremely important.
Maybe one buyer offers slightly more but wants to close three weeks before you're ready to move.
Another buyer offers a little less but can close on the exact date you need.
How much is that convenience worth?
That's a personal decision.
For some sellers, maximizing price is the priority.
For others, avoiding a temporary move, storage, or complicated closing schedule has real value.
That's why I want to understand my seller's goals before we start reviewing offers.
Earnest Money Is Another Piece of the Puzzle
We'll also look at earnest money and the other terms of the contract.
Again, no single item automatically determines whether an offer is good or bad.
The purpose is to look for the combination that provides the seller with the best balance of price, terms, and confidence in reaching closing.
Think of it like assembling a puzzle.
Purchase price is a very large piece.
But it isn't the entire picture.
Multiple Offers Require Strategy
This is one of the parts of real estate where I believe experience really matters.
When several offers arrive, it can be tempting to simply create a spreadsheet, sort the purchase prices from highest to lowest, and pick number one.
But that's not how I approach it.
I want to help my sellers understand:
- What will they potentially net?
- How strong is the financing?
- What contingencies are included?
- What appraisal risk exists?
- Are there seller concessions?
- What is the proposed closing date?
- Does the buyer need to sell another property?
- What are the inspection terms?
- Are there other conditions that could affect the transaction?
Then we talk about priorities.
There Isn't One "Best" Offer for Every Seller
This is an important distinction.
Two sellers could receive the exact same three offers and reasonably choose different ones.
Why?
Because their goals might be completely different.
Seller #1 may already own another home and simply want the highest possible net proceeds.
Seller #2 may be purchasing another home and desperately needs a particular closing date.
Seller #3 may be relocating and value certainty above everything else.
That's why I don't tell my clients, "This is the best offer."
I explain the advantages, disadvantages, and potential risks of each offer so they can decide which one is best for them.
That's an important difference.
Communication With the Other Agent Matters Here Too
In Article 30, I talked about how I communicate with listing agents when representing buyers in multiple-offer situations.
That communication matters on the listing side too.
If I have questions about an offer, I want answers when possible.
Maybe I need clarification about the buyer's financing.
Maybe I want to understand a particular term.
Maybe the closing date doesn't work for my seller, but everything else about the offer is excellent.
Sometimes a phone call between agents can determine whether there's an opportunity to resolve an issue before my seller makes a final decision.
Real estate negotiation isn't simply passing contracts back and forth.
Communication matters.
What Happens If Two Offers Are Very Close?
This is where things can get interesting.
Perhaps we have two strong offers with only a small difference in price.
At that point, we may look much more closely at the details.
Which financing appears stronger?
Which terms better align with the seller's goals?
Which offer presents fewer potential obstacles?
Depending on the circumstances and my seller's instructions, there may also be opportunities to negotiate.
Every multiple-offer situation is different, which is why I don't believe in applying one formula to every sale.
The Goal Isn't Just Getting Under Contract
This is probably the most important point in the entire article.
Our goal isn't to put an "Under Contract" sign on your property.
Our goal is to successfully close the transaction on terms that work for you.
There's a big difference.
An incredible offer that falls apart three weeks later may ultimately be far less valuable than a slightly lower offer that successfully closes.
That doesn't mean choosing the safest offer every time.
It means understanding the balance between potential reward and potential risk.
That's the conversation I want my sellers to have before making their decision.
Final Thoughts
Getting multiple offers on your St. Louis home is a great position to be in.
But it can also make the decision more complicated.
Don't automatically assume the buyer offering the highest purchase price is giving you the best deal.
Look at the entire contract.
Consider the financing.
Evaluate the contingencies.
Understand the appraisal risk.
Look at the closing timeline.
Calculate the potential net proceeds.
And most importantly, decide which combination of price and terms best supports your goals.
When I represent a seller, my role isn't simply to bring them offers.
It's to help them understand what those offers actually mean.
Because ultimately, the best offer isn't necessarily the one with the biggest number.
It's the one that gives you the combination of price, terms, and likelihood of closing that makes the most sense for your particular situation.
Frequently Asked Questions
Should I always accept the highest offer on my house?
No. Purchase price is important, but financing, contingencies, concessions, appraisal terms, inspections, and closing date can all affect the strength and financial value of an offer.
Is a cash offer always better than a financed offer?
No. A cash offer can have advantages, but that doesn't automatically make it the best choice. Price and all other contract terms still need to be evaluated.
What happens if my home doesn't appraise for the offer price?
What happens next depends on the contract and any appraisal-related terms the parties agreed to. This is why it's important to evaluate appraisal risk before accepting an offer rather than waiting until the appraisal is completed.
Is a buyer with a home sale contingency a bad choice?
Not necessarily. A contingent offer can be perfectly workable, but it introduces an additional factor into the transaction. Sellers should understand that risk when comparing it with other offers.
Who decides which offer to accept?
The seller does. My role as the listing agent is to explain the offers, help identify potential advantages and risks, answer questions, and provide guidance. The final decision belongs to the seller.
Selling Your Home?
Get your home's value - our custom reports include accurate and up to date information.